

Does Health Insurance Cover Hair Transplants in the US?
Health insurance in the United States generally does not cover hair transplants because insurers classify most hair restoration procedures as cosmetic surgery. However, certain reconstructive procedures following serious injuries, burns, or medical conditions may qualify for coverage under specific insurance rules.

- Last updated
- 7 reads
- 9 min read
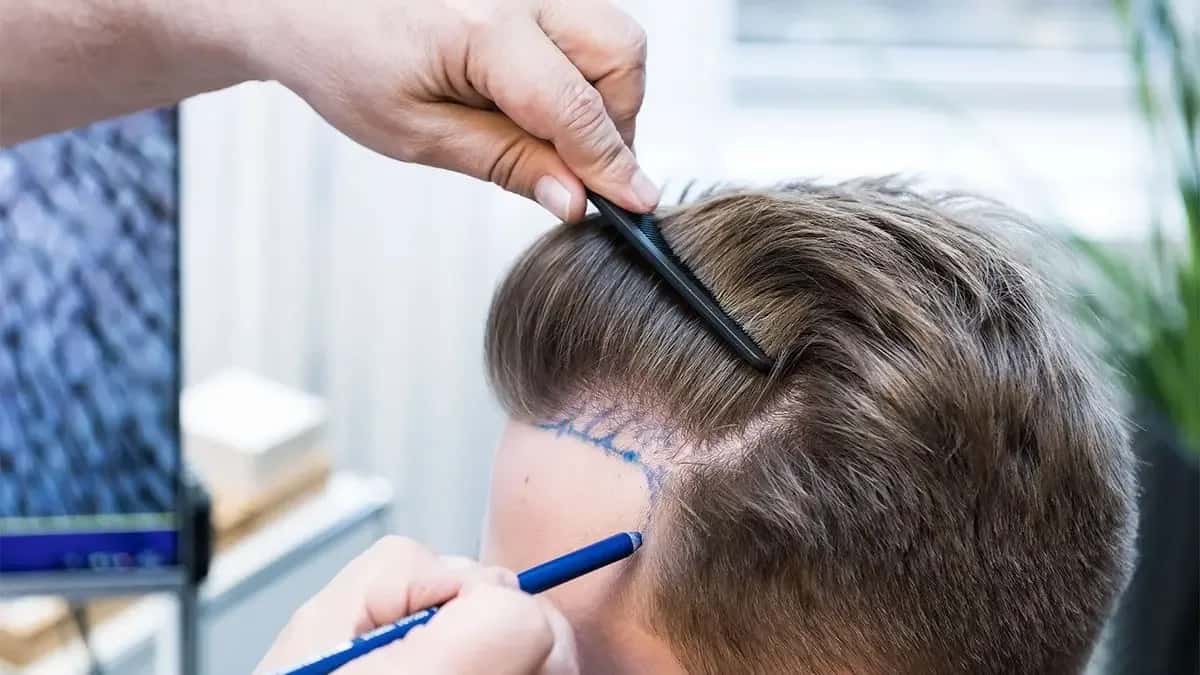


Why Does Health Insurance Usually Not Cover Hair Transplants?
Most health insurance policies distinguish between medically necessary treatment and elective cosmetic procedures. Hair transplantation generally falls into the second category because its primary purpose is to improve hair density, restore a receding hairline, or address baldness rather than treat an underlying illness.
Although hair loss can significantly affect confidence and emotional well-being, these consequences do not automatically establish medical necessity under standard insurance policies. Insurers primarily evaluate whether a procedure treats a medical condition, restores bodily function, or corrects a qualifying physical abnormality.
Common procedures such as follicular unit extraction (FUE) and follicular unit transplantation (FUT) are therefore typically excluded when performed to address hereditary hair loss. This exclusion applies even when the procedure takes place in a medical facility and involves surgical techniques.
As a result, most Americans considering elective hair restoration should expect to pay for the procedure themselves unless their circumstances meet a specific reconstructive coverage exception.
Cosmetic vs Medically Necessary Hair Restoration
Understanding how insurers classify hair restoration procedures is essential when evaluating potential coverage.
Cosmetic Hair Transplantation
Cosmetic hair transplantation focuses on improving appearance by redistributing healthy follicles into areas affected by thinning or baldness. Common reasons include male pattern baldness, female pattern hair loss, receding hairlines, and reduced crown density.
These conditions can have a substantial psychological impact, but insurance policies generally do not consider appearance-related restoration medically necessary solely because hair loss causes distress.
Even when androgenetic alopecia has a medical diagnosis, transplantation usually remains an elective procedure because the surgery primarily improves visible coverage rather than correcting the condition responsible for follicular miniaturization.
Reconstructive Hair Transplantation
Reconstructive hair transplantation addresses hair loss associated with physical damage, severe scarring, or particular medical conditions that have changed the normal structure of the affected area.
For example, someone who experiences extensive burns or undergoes surgery to remove a tumor may require reconstruction to restore an area affected by significant disfigurement.
Some insurance policies recognize qualifying reconstructive treatment as medically necessary, creating a limited possibility of coverage. However, the medical history alone does not guarantee that a hair transplant meets the relevant benefit requirements.
When Can Health Insurance Cover a Hair Transplant?
Coverage exceptions generally involve situations where transplantation forms part of reconstructive treatment rather than elective cosmetic enhancement.
Hair Restoration After Burns or Traumatic Injuries
Severe burns and traumatic injuries can permanently damage hair follicles and create areas of scar tissue where natural hair no longer grows. In certain circumstances, reconstructive procedures may help restore a damaged eyebrow or recreate a hairline affected by the original injury.
Some Medicare coverage rules specifically recognize punch graft hair transplantation for eyebrow reconstruction or symmetrical hairline replacement following qualifying burns, trauma, or tumor removal.
These provisions concern particular procedures and documented reconstructive needs. They should not be interpreted as general insurance coverage for every hair transplant performed after an injury.
Hair Transplants Following Cancer Treatment
Cancer treatment can cause hair loss through chemotherapy, radiation exposure, or surgical removal of affected tissue. While chemotherapy-related hair loss often improves after treatment ends, certain surgical procedures and radiation-related injuries may cause permanent localized hair loss.
Reconstruction following tumor removal can sometimes qualify for consideration when it meets applicable medical necessity requirements. However, a history of cancer does not automatically make subsequent hair transplantation an insured service.
The distinction lies in whether the proposed operation qualifies as reconstructive treatment under the policy rather than whether the person previously experienced a serious illness.
Does Private Health Insurance Cover Hair Transplants?
Private health insurance plans in the United States generally exclude cosmetic hair transplantation. This includes many employer-sponsored policies and individual plans purchased through the Health Insurance Marketplace.
Coverage documents commonly identify cosmetic surgery as an excluded benefit, although reconstructive procedures may receive separate consideration when they meet defined medical criteria.
A policy that provides extensive surgical benefits does not necessarily cover elective hair restoration. Similarly, having a low deductible or comprehensive specialist coverage does not eliminate exclusions for cosmetic procedures.
The most reliable way to establish eligibility is to review the policy's cosmetic and reconstructive surgery provisions and obtain a written coverage determination before proceeding with treatment.
Does Medicare Cover Hair Transplants?
Original Medicare generally excludes cosmetic surgery, including hair transplantation performed solely to improve appearance. However, certain medically necessary reconstructive procedures can qualify when they satisfy applicable coverage requirements.
Some regional Medicare policies specifically address punch graft transplantation used to reconstruct eyebrows or restore a symmetrical hairline after burns, traumatic injury, or tumor removal.
These narrowly defined exceptions do not establish coverage for routine FUE or FUT procedures performed to correct genetic baldness. Medicare Advantage plans must also follow applicable Medicare coverage requirements, although their administrative processes and additional benefits can differ.
Patients considering reconstructive hair restoration should confirm the relevant procedure, diagnosis, coverage criteria, and any authorization requirements before assuming Medicare will contribute toward the cost.
Does Medicaid or TRICARE Pay for Hair Transplant Surgery?
Medicaid coverage follows federal requirements alongside state-specific benefit rules, making it important to distinguish covered reconstructive care from excluded cosmetic services.
Medically necessary reconstruction may receive consideration under applicable Medicaid provisions, but ordinary hair transplantation for pattern baldness is generally not a covered benefit. State benefit documents and managed-care policies provide the relevant coverage conditions.
TRICARE takes a particularly restrictive approach to hair transplantation. Its published reconstructive surgery policy specifically lists hair transplants among excluded procedures, even though other qualifying reconstructive operations may receive coverage.
Having government-sponsored health insurance therefore does not establish eligibility for elective hair restoration.
Can Health Insurance Cover Hair Loss Treatment Without Covering Surgery?
Insurance coverage for diagnosing and treating hair loss is different from coverage for hair transplantation.
A medical evaluation may qualify for benefits when hair shedding results from a suspected medical condition. For example, blood tests investigating thyroid abnormalities, iron deficiency, or other potential causes of hair loss may fall within ordinary diagnostic coverage when medically appropriate.
Some prescription treatments may also qualify for benefits, although medications used primarily for cosmetic hair restoration can face exclusions or formulary restrictions.
These distinctions matter because receiving insurance reimbursement for a dermatology consultation does not mean the same policy will pay for surgical hair restoration.
Patients should evaluate diagnostic services, prescription medication, non-surgical treatment, and transplantation as separate benefit categories rather than assuming coverage for one extends to the others.
How to Check Whether Your Hair Transplant Is Covered
Determining insurance eligibility requires more than asking whether a policy includes surgical procedures. The relevant question is whether the proposed hair restoration service meets its specific medical necessity and benefit requirements.
Begin by reviewing the Summary of Benefits and Coverage alongside the full insurance policy. Look for provisions addressing cosmetic surgery, reconstructive procedures, hair transplantation, medical necessity, and excluded services.
For a potentially reconstructive procedure, supporting records may include the original diagnosis, surgical history, evidence of scarring, photographs, and an explanation of the proposed treatment.
The insurer may also request procedure and diagnosis codes to determine whether the service meets its coverage criteria.
Written confirmation is particularly important because verbal explanations do not replace a formal benefit determination. Even when prior authorization is granted, applicable deductibles, coinsurance, and other conditions may still affect the patient's financial responsibility.
What Happens If Insurance Denies Hair Transplant Coverage?
An insurance denial does not always represent the end of the review process, especially when the request involves a documented reconstructive condition.
The first step is to examine the denial explanation and identify whether the insurer rejected the procedure as cosmetic, excluded it under the benefit contract, or determined that the submitted medical documentation was insufficient.
A reconsideration or appeal may be appropriate when the available records demonstrate that the proposed procedure satisfies an applicable reconstructive coverage provision.
Additional documentation can help clarify the nature of the original injury, the resulting abnormality, and the medical purpose of the requested operation.
However, an appeal cannot automatically override an explicit benefit exclusion. If the policy categorically excludes the proposed transplantation procedure, medical documentation alone may not establish eligibility.
How Much Does a Hair Transplant Cost in the US Without Insurance?
Because insurance rarely covers elective hair transplantation, understanding the expected out-of-pocket expense becomes an essential part of financial planning.
Hair transplant procedures in the United States commonly cost approximately $6,000 to $15,000, while smaller sessions may fall below this range and extensive procedures can exceed $20,000.
The total cost depends on the number of grafts required, the extraction technique, the extent of hair loss, and the resources involved in performing the surgery.
FUE generally involves extracting individual follicular units, while FUT involves removing a strip of donor tissue before separating it into grafts. Both procedures require surgical planning and careful graft placement, although their pricing structures may differ.
A detailed overview of hair transplantation in the United States provides additional information about treatment methods, expected expenses, and considerations involved in planning the procedure.
Patients should also account for postoperative medication, follow-up appointments, travel, and potential additional treatment sessions when assessing the complete financial commitment.
Can You Use HSA or FSA Funds for a Hair Transplant?
Health Savings Accounts (HSAs) and Flexible Spending Accounts (FSAs) allow eligible medical expenses to be paid using funds that receive favorable tax treatment.
However, standard cosmetic hair transplantation generally does not qualify as an eligible medical expense under federal tax rules.
Certain reconstructive procedures necessary to correct deformities caused by congenital abnormalities, accidental injuries, or disfiguring diseases may qualify under specific circumstances.
This exception does not mean that every medically documented hair loss condition makes transplantation eligible for tax-advantaged payment.
Using HSA funds for a nonqualified cosmetic procedure can trigger taxes and potentially additional penalties. FSA reimbursement may also be denied when an expense falls outside the applicable eligibility rules.
For this reason, patients should verify the expense's qualification before using either account to fund surgery.
How to Pay for a Hair Transplant Without Insurance
When hair transplantation is not covered, patients commonly use personal savings, structured payment arrangements, or healthcare financing.
Some financing options divide the procedure cost into monthly payments, although interest rates, introductory offers, and repayment terms can significantly influence the final amount paid.
Comparing the complete cost of treatment is more useful than focusing exclusively on the advertised monthly installment.
Patients can also evaluate different extraction techniques and graft requirements to understand how their treatment plan influences the total expense.
Reviewing hair transplant prices and cost factors can help clarify the financial considerations involved before committing to a procedure.
Regardless of the payment method, a written estimate should identify the included services and explain any additional charges that may arise.
Frequently Asked Questions About Hair Transplant Insurance Coverage
The following questions address common concerns about whether health insurance will contribute toward hair restoration expenses in the United States.
-
Will insurance cover a hair transplant for male pattern baldness? Male pattern baldness is generally considered a cosmetic indication for hair transplantation, even though androgenetic alopecia is a recognized medical condition. Most insurance policies exclude surgical hair restoration when its purpose is to improve appearance rather than satisfy a qualifying reconstructive need.
-
Can insurance pay for hair transplantation after an accident? Certain reconstructive procedures following serious burns, trauma, or tumor removal may qualify under specific coverage provisions. Eligibility requires the proposed operation to meet the relevant criteria, and the presence of permanent hair loss after an accident does not independently guarantee payment.
-
Does health insurance cover hair transplants for women? Insurance policies generally apply the same cosmetic surgery exclusions to female and male patients, making routine transplantation for female pattern hair loss an out-of-pocket expense. A reconstructive indication may receive separate consideration when the procedure satisfies applicable coverage requirements.
- Last updated
- Language
- English
How did you find this article?
Certain dietary supplements can cause hair loss when taken in excessive amounts, particularly products containing high doses of vitamin A, selenium, or other concentrated nutrients. While supplements can help correct nutritional deficiencies that affect hair growth.
Spironolactone for female hair loss can help slow progressive thinning and improve hair density by reducing the effects of androgens on sensitive hair follicles. Although this prescription medication is not specifically approved for hair loss, clinical research supports its use in selected women.
Ginseng for hair loss has attracted scientific interest because its active compounds may support hair follicle activity and influence the natural hair growth cycle. Although laboratory findings and small clinical studies suggest potential benefits.
Subscribe to the Medifinder newsletter and never miss our latest content.