

Does Health Insurance Cover Gastric Bypass?
A practical guide to bariatric surgery coverage, medical necessity, eligibility criteria, pre-authorization and out-of-pocket costs.

- Last updated
- 8 reads
- 6 min read
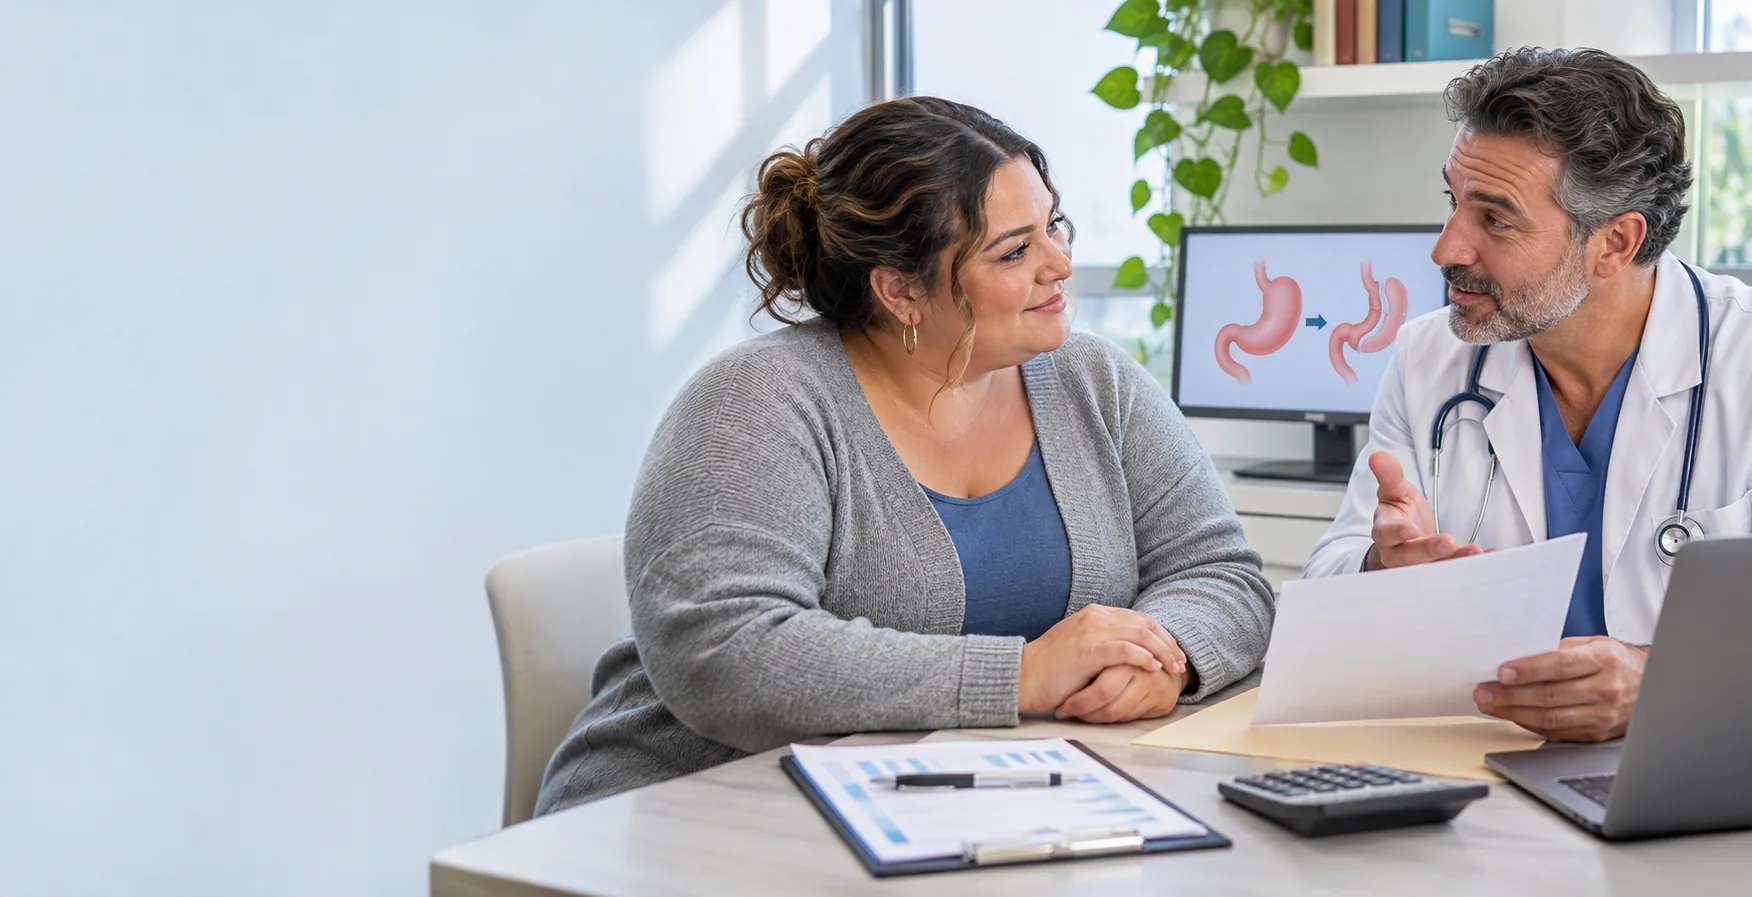


Gastric bypass is a major metabolic operation that can support significant weight loss and improve obesity-related conditions. Because it is more complex than a lifestyle program, many patients ask whether their health insurance will pay for it. The answer is shaped by medical necessity, policy exclusions, eligibility criteria and the approval process. Knowing how insurers assess the operation can help patients prepare the right documents and avoid unexpected costs.
Does Health Insurance Cover Gastric Bypass?
Health insurance may cover gastric bypass when the operation is classified as medically necessary treatment for severe obesity and related health risks. Coverage is less likely when a plan excludes bariatric surgery, when the patient does not meet the policy’s criteria or when the required pre-authorization has not been completed.
Unlike an appearance-focused procedure, gastric bypass is intended to change digestion and metabolism. Insurers may consider it when excess weight is associated with conditions such as type 2 diabetes, high blood pressure, sleep apnea, fatty liver disease or significant limitations in daily life. The presence of a diagnosis alone does not guarantee approval. The plan usually reviews the full medical history and the patient’s previous attempts to manage weight.
Why Medical Necessity Is Central to the Decision
Medical necessity means that the operation is appropriate for a documented health problem and is expected to provide meaningful clinical benefit. Each plan defines this concept differently, but many policies look at body mass index, obesity-related diseases, previous treatment and the expected risk of leaving the condition untreated.
The insurer is not only asking whether the patient wants to lose weight. It is asking whether surgery is a reasonable treatment for a serious, persistent condition after other approaches have not produced adequate results. A detailed assessment from a bariatric team can show how weight has affected physical health, mobility, medication needs and long-term risk.
Typical Eligibility Factors
Policies often use a combination of body mass index and related medical conditions. Some require a higher body mass index without other diseases, while others consider a lower threshold when diabetes, obstructive sleep apnea, hypertension or another serious condition is present. Age limits, previous operations and general fitness for anesthesia may also appear in the criteria.
Insurers can require evidence that the patient has participated in supervised weight-management care. This may include nutrition visits, physical activity planning, behavioral support or prescribed medication. The purpose is not to punish someone for needing surgery. It helps the plan confirm that surgery is being recommended as part of a structured treatment pathway rather than as a first response to a short-term weight change.
What Is the Pre-Authorization Process?
Pre-authorization is a formal review completed before surgery. The bariatric team typically sends the diagnosis, body mass index history, related conditions, previous treatments, psychological assessment and proposed procedure. The insurer evaluates whether the request meets the policy’s criteria and whether the surgeon and hospital are eligible providers.
Patients should request a written decision that lists the approved procedure and the services included. Ask whether the authorization covers the surgeon, anesthesia, hospital stay, laboratory tests, imaging, nutritional supplements and postoperative visits. An approval for the operation does not always mean every related service is paid in full.
Documents That Can Support the Claim
A complete file may include medical records from primary care, endocrinology, cardiology, sleep medicine or other relevant specialties. Blood test results, sleep studies, blood pressure records, medication lists and a history of weight-management attempts can help the reviewer understand the overall health picture.
The surgeon’s letter should explain why gastric bypass is being recommended, what complications of obesity are present and why the expected benefits outweigh the surgical risks. Nutrition and behavioral assessments can demonstrate readiness for the dietary changes required after surgery. Records should be consistent, current and easy to follow.
Why the Supervised Weight-Loss Requirement Matters
Some policies require several months of documented, supervised weight management before they will review bariatric surgery. The program may include regular visits and measurable goals rather than a single consultation. Missing appointments or incomplete records can delay the authorization even when the patient appears medically eligible.
Keep copies of appointment summaries, meal plans, exercise goals and prescribed medicines. Ask the provider to record weight changes, barriers and the response to each intervention. If the program is interrupted by a medical problem, explain the interruption in writing so it is not mistaken for a lack of commitment.
Common Exclusions and Limitations
Some plans exclude bariatric surgery entirely or cover only certain procedures. Others impose waiting periods, lifetime benefit limits, network restrictions or requirements for treatment at an accredited facility. A policy may also exclude complications related to surgery performed outside the approved network.
Revisional operations can be reviewed differently from a first gastric bypass. A revision may be covered when it treats a documented complication, but it may be excluded when requested solely because weight loss was less than expected. Nutritional supplements, plastic surgery after major weight loss and travel expenses are often handled separately.
What If the Operation Is Considered Elective?
A claim can be denied when the insurer believes the patient does not meet the medical criteria or when the plan classifies the operation as excluded elective treatment. The denial should identify the reason, the policy section and the appeal deadline. Patients should ask for the clinical criteria used in the review.
An appeal is stronger when it adds relevant evidence rather than repeating the original request. Updated medical notes, a clearer record of supervised treatment, proof of related disease or a detailed explanation from the bariatric surgeon may address the concern. Submit the appeal within the stated time and keep confirmation that it was received.
How Much Could the Patient Still Pay?
Even with approval, patients may face a deductible, co-insurance or a fixed hospital contribution. Out-of-network charges can be substantial, especially if the surgeon, anesthetist and facility do not all participate in the same network. Ask for a written estimate that separates covered, partially covered and excluded services.
Additional expenses may include preoperative tests, nutritional products, prescription medicines, transport, time away from work and treatment of unrelated conditions. A clear estimate helps patients compare options without focusing only on the headline price of the operation.
Questions to Ask the Insurer and Surgical Team
Ask the insurer whether the plan covers gastric bypass, what body mass index and medical conditions are required, how long supervised treatment must continue and whether a referral is necessary. Confirm the pre-authorization deadline and the documents that must be submitted.
Ask the surgical team which hospital and anesthesia providers are in network, whether the program includes nutrition and behavioral support and what happens if the procedure is postponed. Clarify how complications, readmission and future revision surgery would be handled under the plan.
Frequently Asked Questions About Gastric Bypass and Insurance
Will insurance cover gastric bypass for weight loss alone?
Coverage is more likely when severe obesity and related health risks are documented. A request based only on a desire to lose weight may not meet the plan’s medical-necessity criteria.
Do I need to try dieting before surgery is approved?
Many policies require a documented period of supervised weight management, although the length and exact requirements differ between plans.
Does approval include the hospital stay?
The hospital stay may be included, but the authorization should be checked for facility, surgeon, anesthesia, tests and postoperative services separately.
What can cause a bariatric surgery claim to be denied?
Common reasons include an exclusion in the policy, missing pre-authorization, insufficient medical records, failure to meet eligibility criteria or treatment outside the approved network.
Can I appeal a denial?
Most plans provide an appeal route. The appeal should address the stated reason for denial and include any missing clinical evidence before the deadline.
Final Perspective
Health insurance may cover gastric bypass when it is presented as medically necessary treatment for severe obesity and documented health complications. Approval usually depends on eligibility thresholds, supervised weight-management records, a complete medical assessment and formal pre-authorization. Patients should review exclusions, confirm network participation, request a written benefit decision and calculate their remaining costs before scheduling surgery. Careful preparation turns a confusing insurance question into a process with clear steps, evidence and realistic expectations.
- Last updated
- Language
- English
How did you find this article?
Understand what Ozempic Face means, why rapid weight loss can change facial volume, and which skin-care and cosmetic options may help.
A clear guide to gastric balloon side effects, serious complications, warning signs, recovery and practical questions to ask before treatment.
This guide explains healthy fasting blood sugar levels, prediabetes and diabetes ranges, testing requirements, common causes of abnormal results, and how fasting glucose should be interpreted.
Subscribe to the Medifinder newsletter and never miss our latest content.